 CLUJUST Justitie. Stiri. Anchete. Procese. Avocati. Sistemul judiciar. Interviuri. Jurisprudenta. Portal. Cluj.


Several courts were obliged to deal with some complaints of ANAFI in the context in which the IRS had refused initially to deal with them on the grounds that the expected settlement of criminal referrals made, in parallel, in those cases. Lawyers for SCA in Cluj and Idea Associations, who have obtained their clients such verdicts, recommends all to not sit on hold and ask the Court to force the IRS to resolve an opposition to them and allow them to apply to the Court with an action for annulment of the Act by which they are established payment obligations.
Profit.ro recently announced that half of the contested sums to Fisc sit unresolved whereas inspectors have done in parallel, criminal complaints that block analysis. In these circumstances, the companies are nemulțumite controls need to wait for the resolution, while I get to risk insolvency, either because they are forced to pay obligations in addition to the budget and don't have the money or because they have protective measures on the assets.
Lawyers from ACS and associations of Cluj this idea shows that companies can not stand idle, with the sword above his head, insolvency and to ask the courts to compel National Tax Agency to proactively deal with the challenges to them in various decisions. In many cases, the shares have been admitted in the first instance.
As I write the folks at Profit.ro, NAFA has suspended the procedure of review procedures with almost 50% of the total tax claims contested between the year 2015. In recent years is becoming more visible to seize ANAF conduct the prosecution to investigate certain facts which, according to the tax inspectors, would bring together the constituent elements of criminal offences.
Thus, the tax inspection "appreciates" the Commission of fraud by the taxpayer and take advantage of this "appreciation", setting out its claims in additional tax burden. Concurrent with the issuance of the decision imposing the tax inspection, refer the matter to the prosecution, asking them to verify that the "appreciation" for the existence of fraud is correct or not.
To defend themselves, the taxpayer is obliged to address the administrative complaint with the IRS, but it is not resolved, the dispute settlement procedure being suspended. More specifically, the dispute settlement body that cannot rule before settling down in criminal if there is really a fraud. In other words, the tax inspection is 100% convinced of the existence of fraud and establishes the responsibility of the taxpayer is required to pay but when taxpayer shall defend, appeal settlement body no longer is convinced that fraud exists and shall suspend the procedure for the settlement of the appeal until its criminal enforcement agencies say.
Considering that access to the courts, with an action involving the annulment of the decision to impose additional tax claims and determined on the basis of "appreciation" of the tax inspection is not possible until the opposition is not resolved, the taxpayer is put in a position to be executed for tax claims, without having the opportunity to reach a court in which to prove his innocence. Because, as surprising as it may sound, the taxpayer is always guilty until proved otherwise.
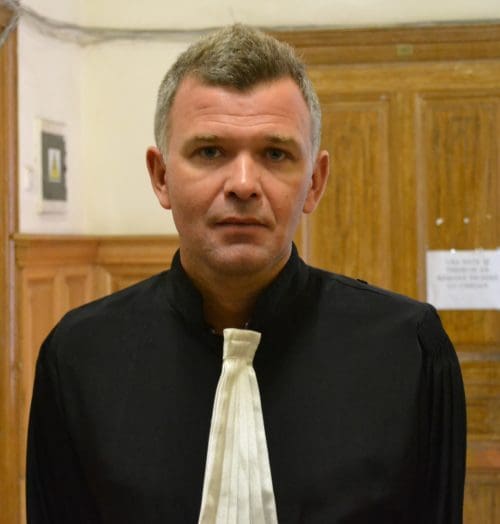
In these circumstances, the taxpayer has two options: either to accept the situation, to wait for a solution from criminal and, until then, to survive, or request the Court to force the IRS to resolve an opposition and allowing him to address the Court with an action for annulment of the Act by which it is established the payment obligations. Many contributors, I think from neștiință, take the first option. We offer our clients the second variant and I obtained through solutions that have been found to nelegalitatea solutions for stay of proceedings pending the appeal, the IRS was compelled to appeals, and taxpayer was opened by a court in which to discuss how the nelegalitatea were established in additional tax claims task. ", said lawyer Abby Carr (pictured) from Idea and associations Clujust.ro
We present below some data in these sentences make sense, in the period July-September. The first three are from the Tribunal, and the last of the Court of appeal.
(File/85 977/2016) Solution brief:
"Administrative action Admits formulated applicant SC b. LLC, inconsistent with the defendant General Directorate of public finance Regional Brasov-Service Complaints Appeals.

For rent in part Commission decision No. 9804/21.03.2013 issued by the defendant, in terms of the point. 1 of its device and compel the defendant to settle the contestatia formulated by the applicant against the decision of tax no. Nr. F-SB285/19.08.2015 issued by the County Administration of public finance-Tax inspection Activity, which was rejected at the amount of 224,226 lei repayment representing the VAT. Without expenses. With the right to appeal within 15 days of the notice. "
(File/85/979 2016) Solution brief:
"Administrative action Admits formulated by the applicant in SC, BANTUT inconsistent with the defendant Regional Directorate of public finance.
Cancels the decision No. 10145/22.03.2016 issued by the defendant and compel the defendant to settle the contestatia formulated by the applicant against the decision of tax no. F-SB335/18.09.2015 issued by the County Administration of public finance-Tax inspection Activity, which was rejected at the amount of 123,509 lei repayment representing the VAT. Without expenses. With the right to appeal within 15 days of the notice. The request and the grounds of appeal shall be lodged with the Court. Pronounced in public session of 12.07.2016.
(File/85/822-2016) Solution brief:
Recognizes the administrative action. Cancels the decision No. 993/12.10.2015 issued by DGRFP. Compel the defendant to examine on the merits of the complainant formulated contestatia against the decision imposing no. SB 600/f 19.12.2014
compel the defendant to pay the sum of 70 lei and expenses. With the right of appeal, registered at the Court, within 15 days following the communication

(File 355/57/2016) Solution brief:
"Admitting the complainant formulated action S.C. THE JOINT-STOCK COMPANY controversy with the defendant National Agency for tax administration-General Direction of solving Challenges and consequently:
Cancels the decision on resolving the appeal No. 72/08.03.2016 issued by the defendant and the obligation to solve the contestatia background of the applicant formulated administrative decision imposing no. F-MC 2301/12.11.2015, issued on the basis of the report of the AMTI nr. F-MC 311/12.11.2015. With the right to appeal within 15 days of receipt, by application lodged at the Court of appeal. "

